
Independently compiled Annual Financial Statements?
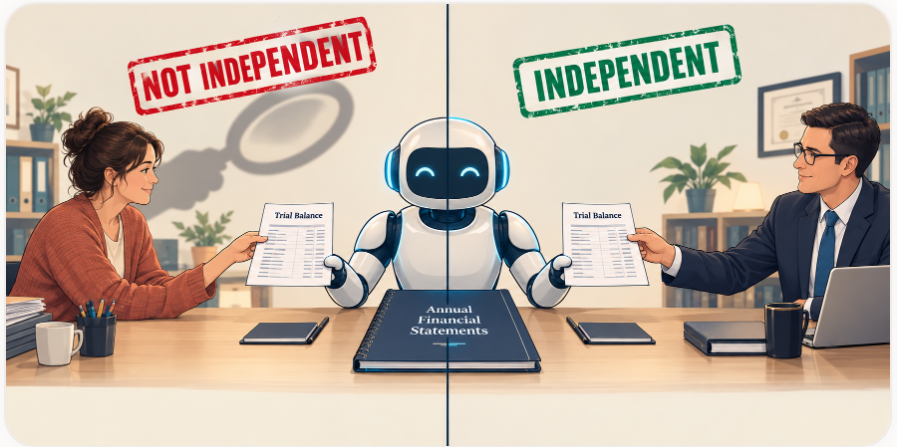
Here’s an interesting one. In terms of the Companies Act, having a company’s Annual Financial Statements compiled independently often reduces the verification (review or audit) requirements.
Now, that was all before AI. It is now possible to give AI a Trial Balance and tell it to draft to International Financial Reporting Standards. You can’t get much more independent than that can you?
So, where does that leave us? Let’s have a look at Regulation 26(1)(e) which defines “Independently compiled and reported”
“independently compiled and reported” means that the annual financial statements are prepared—
(i) by an independent accounting professional;
(ii) on the basis of financial records provided by the company; and
(iii) in accordance with any relevant financial reporting standards
So, (i) says that AI produced AFS are not independently compiled if the bookkeeper fed it the Trial Balance.
But they would have been independently compiled if I, as a CA(SA), fed the same Trial Balance to the same AI.
And on that distinction hangs whether the AFS need not be Reviewed, must be Reviewed or must be Audited.
One of the unanticipated consquences of AI!
4 comments
Reply


For “independent” I think the issue of whether the AI (or any other service provider) has agency to question the information provided is also important, regardless of who provides the source information.
Hi again Dave. No, I disagree, simply because “Independent” is defined, so it is not a question of interpretation.
Please advise , is audit or review not determined in terms of PSI scorecard – does an independent compilation override the PSI scorecard requirements for audit or review , I don’t believe
Hi Haroon,
No it does not override the PIS, but there is a decision tree of which PIS us only one component. Owner managed is another. In house or independent compilation is another.