
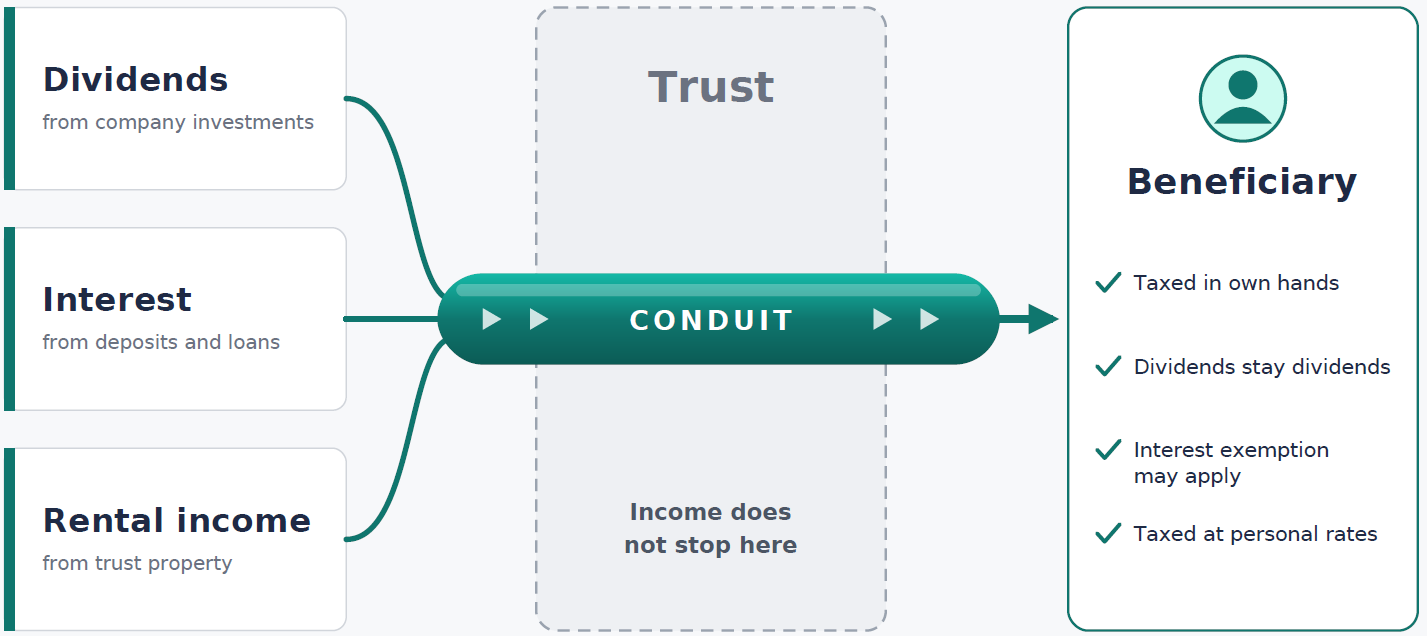
A conduit is a pipe. So, imagine a pipe going through your trust. Income received by the trust can flow though that pipe to a beneficiary without touching the trust, provided it does so before the new tax year starts. It is as if the trust was not there. So, the income stays unchanged. CGT remains CGT, taxable income remains taxable income, interest remains interest. And it is treated normally in the hands of the Beneficiary. The individual allowances still apply.Because trusts are taxed at 45% (or 36% for Capital gains) and individual beneficiaries are normally taxed at a lower…
Trusts and Estate Planning
Many of these transfers involve a company whose shares are worth R100 or so. Securities Transfer Tax is .25% of the value of the shares and by my reckoning that’s 25c.So, to submit an STT return or not? I’m thinking if you don’t, SARS can hit you with double penalties. That totals a whopping 75c. Ouch!Fortunately, Section 8(1)(r) of the Securities Transfer Tax Act comes to our rescue. No tax is paid for company share transactions below R40 000. Whew! Saved after all.

First rule – Don’t ask AI to draft the trust deed.Second rule – Don’t ask an attorney to draft the trust deed.Third rule – You only need one trust despite what the trust pedlars tell you.Get those three things right and you stand a chance of getting the whole job right. There are numerous documents that have to be completed. Then, if you are resident within the juristiction of the Pretoria or Johannesburg Masters of the High Court, the application must be made online, a laborious and frustrating process. The website is so slow, it dumps you for inactivity because…
This is such a common perception that one can’t help wondering how it started.Perhaps because trusts are taxed at 45%. I can think of no other reason. So let’s deal with that one.A properly constructed trust will never pay tax. Why? Because the only assets it should own are shares in companies and, possibly, non-income producing assets such as the founder’s home.Companies are taxed at 27% and that’s where all the action is. In the unlikely event that the company declares a dividend, it will be subject to 20% Dividends Withholding Tax whether it is owned by a trust or…

No, No and No again! Why not? Because AI will search through whatever trust deeds it can find, bung them all together, strip out the obvious rubbish and present the result as its own draft. That’s exactly what an attorney will do if you ask him/her to draft you a trust deed, except for the bit about stripping out the obvious rubbish. I tried it, just for fun, and I quickly recognised many of the mistakes that I see in trust deeds (and I’ve seen hundreds of them) and which led me to devote a whole chapter of my book…

I very occasionally run across an attorney who can both read and actually use his/her brain to interpret what he/she has read in the statutes and that happened this week. I owe this one to Cobus Welgemoed, Conveyancer who asked me this question

Last month I talked about moving a service company into a trust. If the company owns assets, such as plant and machinery, then it gets a bit more complicated. The principal is basically the same. You register a new company and issue the shares to your trust. Then you start invoicing from the new company (increasing its value), but continue paying the bulk of the expenses in the old one (reducing its value). The old company rents the assets to the new company, and here you can play around with rentals to balance the profits and expenses to the best…

The first question is, of course, what do you mean by “wealthy”? I like my definition of being “reasonably wealthy” as “having enough passive income to be able to retire”. For us average people, there is, in my view, only one way to achieve this other than by gambling successfully and that is by investing in property. Why property? Because you can buy a R900 000 property with R90 000. You can’t buy R900 000 worth of listed shares except with R900 000. You will need about R12m to 14m invested in rental earning property to be able to retire,…

The shares in your company cost you R120 or R100 depending on whether we registered the company or someone else did and they are now worth R1m. Incidentally, the reason we issue 120 shares is that 120 can be divided by 1, 2, 3, 4, 5 and 6, so you can have any of those numbers of equal shareholders. You now want the company to be owned by your trust. You can donate it and pay 20% Donations Tax on R1m – R150K (the Annual allowance) or sell it and pay up to 18% CGT on R1m – R120 (the…

My AI generated weekly update advises me that from 4th May 2026, SARS will be imposing monthly administrative penalties on trusts that fail to submit their annual tax returns. This was gazetted on 27 March and specifically confirms that, as is the case with companies, it will apply even when the trust earns zero income. The probability is that the penalties will be R250 per month for every outstanding tax return. Since posting this article, we have received, on 5th May, our first notification of the imposition of R250 per return for a trust. So, it’s real and it’s happening.…

You’ve lent money to your trust’s company, perhaps for a deposit on a property purchase or perhaps from selling your property to the trust when it didn’t have the money to pay you. Either way s7C of the Income Tax Act kicks in. In simple terms, it says that you must charge interest at least at the official rate (which is the repo rate plus 1%). If you don’t, then the shortfall that you didn’t charge is deemed to be a donation and that is subject to Donations Tax at 20%. Now it gets interesting. If you don’t earn any…

This is one of the most frequently asked questions during my many Teams meetings. So, here’s the answer. I’ll talk as if you only have one property to deal with. You have to choose between donating the property or selling it. There’s no other way. If you donate it, you’re in for 20% Donations Tax. The only advantage is that you will have moved its value out of your estate and away from your creditors. You can’t do this to escape creditors whom you know are already proceeding against you. Your alternative is to sell it, but the trust has…

Yes, you can, but for all tax purposes, it will be deemed to have been sold at market value. So, why mess with the price? You will probably be selling to a company owned by the trust. If the company does not have the money to pay for the property then it will owe you the money and s7C of the Income Tax Act says that you must charge interest at least at the official rate. That interest is taxable in your hands. So, the lower the actual selling price, the lower the Conveyancer’s fees and the lower the tax…

If ever you, as a trustee, are required to sign surety to enable a trust owned company to raise a bond, guaranteed that it’s by First National Bank. They are clueless with regard to a shareholder’s responsibilities to a company. So, if you get this demand from FNB, here’s what you do: Respond that one of the trustees refused to sign on the grounds that it is an improper requirement to ask a shareholder to sign surety for a company. In every instance where I have been involved, they have backed down. Most recently, by saying that since the trust…

Oddly enough, SARS has not yet latched onto one way in which they can legitimately, and in my view should, attack trusts. But let’s first answer the question. The answer? Categorically, No. I have seen no evidence whatsoever that SARS is, or has any intention of, targeting trusts. So, where does this common misperception come from? Simply the fact that trusts are taxed at a flat 45%. But a properly built trust structure ensures that the trust never earns taxable income and is therefore never taxed. So, the 45% becomes irrelevant. Then where can SARS attack trusts? There’s a provision…

I owe this thought provoker to my old friend Marc Quatember, a Director of Maximus Wealth Managment.He had drawn up an Estate plan and included Executors’ fees of 4.025% which I queried. He responded that it was 3,5% + VAT.So, that raised the question “When should an Executor charge VAT on fees?”If he (my apologies ladies, but writing his/her etc. is just too cumbersome) has been appointed in his own capacity as an individual and is not VAT registered, then his practice (or employer) will not invoice the fees, and he will not charge VAT.If he is VAT registered, or…

This one arose when we had a trust that owned fixed property. We wanted to convert an existing CC to a company, then use s42 to slot it between the trust and the property. The problem was that a CC does not have authorised capital, so the members are in total always 100% owners of the CC. s42 requires the issue of new shares in exchange for the asset, but if the authorised share capital after conversion was only 100 shares, we would have to first increase the authorised share capital before we could do the s42 asset for share…

The Transfer Duties Act defines “Property” as including the shares of a residential property company so, the sale of those shares attracts Transfer Duty. It also often attracts CGT. Let’s take an example. You own a company that bought a residential property for rental. The net Asset Value of the company started at R100 and has now grown to R3m due to the growth in value of the property. Now, you want to sell the shares to the trust that you registered back in 2020. My first question would be “What was the last tax year for which you submitted…

s54 of the Income Tax Act imposes Donations Tax on the South African donor irrespective of to whom the donation is made. So yes, once you have used up your R100 000 annual allowance, such a donation would be subject to the 20% tax.

Firstly, you need to distinguish between once only costs and ongoing costs. Often, the ongoing costs can be reduced if you do the work yourself. Note that trust assets are not protected from your creditors if you do not have an independent professional trustee, which is why that is a discretionary cost. These are all the possible costs. You need to cherry pick those that will apply to you.